Why Securing Preapproval Before House Hunting Matters
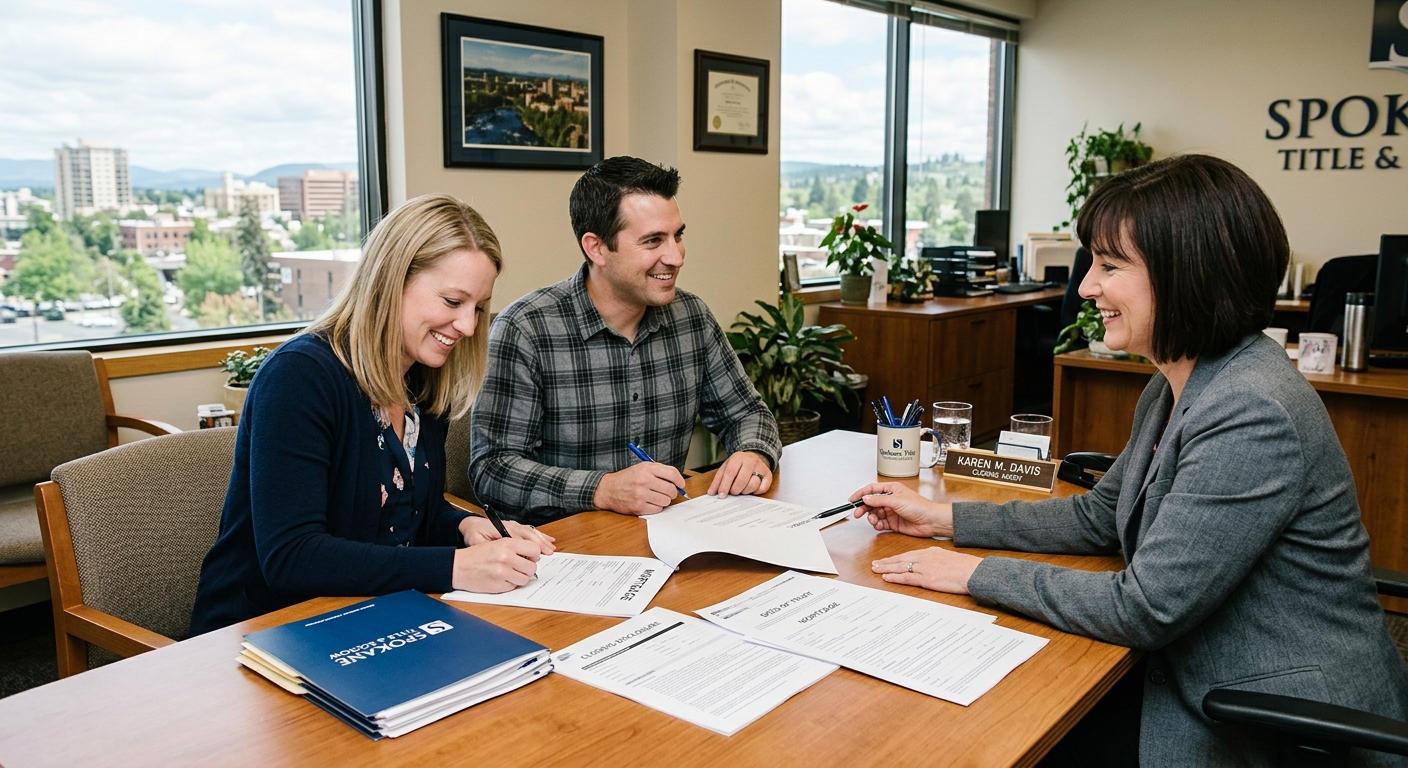
Obtaining mortgage preapproval means submitting your financial details to a lender so they can assess how much you are eligible to borrow before you make any offers on properties. The documentation required during this stage typically includes recent pay stubs, federal tax returns from the past two years, bank statements, and a valid form of identification. Laura Wells and her experienced team evaluate this information and produce a preapproval letter that real estate agents and home sellers view as evidence of your financial readiness. Your preapproval amount reflects your total income, existing debt obligations, credit score, and available assets. Completing this step prior to attending open houses or scheduling showings significantly strengthens your negotiating position when you identify the right property in the Spokane area.
 Frequently Asked Questions