Smart Mortgage Decisions Every California Homebuyer Should Make

The California housing market moves fast, and borrowers who walk in unprepared often find themselves losing deals over financing issues that could have been avoided. From the first application to the final closing, the decisions you make during the loan process shape the outcome. Matt Roth Mortgage in La Mesa has guided California buyers and investors through these complexities for close to thirty years. A well-structured approach from the outset puts you ahead of the competition. Among the most consequential steps any buyer can take is obtaining full underwriting approval well before submitting an offer, rather than settling for a surface-level prequalification. A thoroughly verified home loan preapproval demonstrates to sellers that your financing is backed by real documentation and lender review. California's demanding real estate environment offers little tolerance for financing gaps or unexpected delays. Whether you are buying a primary residence or pursuing investment property financing, understanding your loan options early strengthens both your offer and your negotiating position.

Smart Mortgage Decisions Every California Homebuyer Should Make

The Real Value of Full Underwriting Approval Before Submitting an Offer

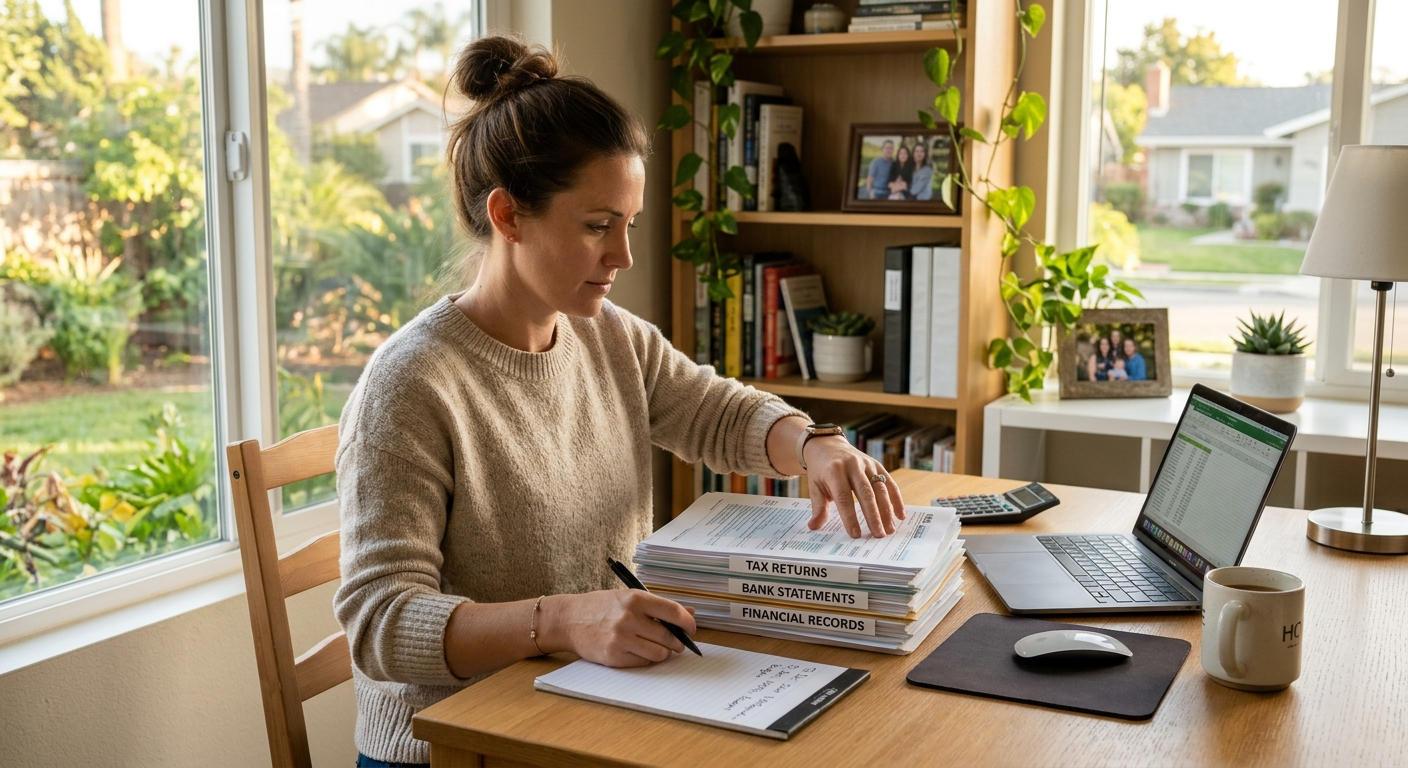
A large share of California buyers enter the market with only a prequalification letter in hand, a document built on self-reported figures that sellers and their agents view with limited confidence. Full underwriting approval, by contrast, means a lender has already verified your tax returns, employment history, bank statements, credit profile, and assets before you set foot in a property. This level of preparation eliminates major financing contingencies and sends a clear signal that your offer is likely to close. In markets where three or four competing bids arrive simultaneously, having verified approval is a tangible edge. Bypassing this step ranks among the most consequential home loan missteps buyers make, often resulting in last-minute underwriting problems or outright denials after a purchase contract is already in place.
The Real Value of Full Underwriting Approval Before Submitting an Offer

Loan Programs Designed for California's Diverse Borrower Landscape

California's borrower pool spans a wide range of financial profiles, and a single conventional loan product rarely fits everyone's needs. Self-employed individuals, seasoned real estate investors, and high-net-worth buyers often find that non-QM loans offer a better path forward, using bank statement deposits or asset-based income documentation in place of traditional tax return analysis. For landlords and investors prioritizing rental cash flow, DSCR loans assess a property's income potential rather than the borrower's personal earnings, making investment property financing considerably more attainable. For buyers pursuing higher-priced California real estate, jumbo loan products can provide financing up to five million dollars based on creditworthiness and down payment strength. Visiting Matt Roth Mortgage's La Mesa page offers a comprehensive overview of available programs suited to buyers and investors across varied financial situations.
Loan Programs Designed for California's Diverse Borrower Landscape

Key Preparation Habits That Protect Your Loan From Start to Closing

Steering clear of costly professional mortgage mistakes in La Mesa and throughout California begins with understanding what lenders scrutinize at every stage of the process. Borrowers who switch employers, open new credit accounts, or make unexplained large deposits while their loan is in underwriting frequently cause delays or trigger outright denials. Financial stability from initial application through closing day is critical. Assembling two years of tax returns, consecutive pay stubs, and recent bank statements before you apply eliminates documentation gaps that slow the review process. Partnering with a lender who communicates clearly at each stage, rather than one who rushes through disclosures, significantly lowers the risk of errors that become difficult or impossible to correct after a purchase agreement is executed.
Key Preparation Habits That Protect Your Loan From Start to Closing

Frequently Asked Questions

Prequalification is an informal estimate grounded in self-reported data that has not been verified. Full underwriting approval means a lender has examined and confirmed your income documentation, asset accounts, and credit history, giving both sellers and agents far greater assurance that the transaction will reach closing successfully.

DSCR loans qualify borrowers based on a rental property's debt service coverage ratio rather than personal income. They are well suited for real estate investors who have strong property cash flow but complex or variable personal income that is difficult to document traditionally.

A non-QM loan relies on alternative income documentation, such as bank statement deposits or asset depletion calculations, rather than conventional income verification through tax returns. It is particularly well suited for self-employed professionals, independent contractors, and high-net-worth individuals whose returns understate their true financial capacity.

Jumbo loans apply to loan amounts that exceed the standard conforming limits. In California, jumbo financing is available for high-value properties, with select lenders offering products up to five million dollars depending on the borrower's credit strength, reserves, and down payment contribution.

Common missteps include relying on prequalification instead of full underwriting approval, changing employment mid-process, taking on new debt after application, and failing to disclose all financial accounts. Each can delay or derail a closing that seemed straightforward. Learn more about avoiding mortgage mistakes before submitting an offer.