Quantitative Risk Analytics Built for Institutional Portfolios

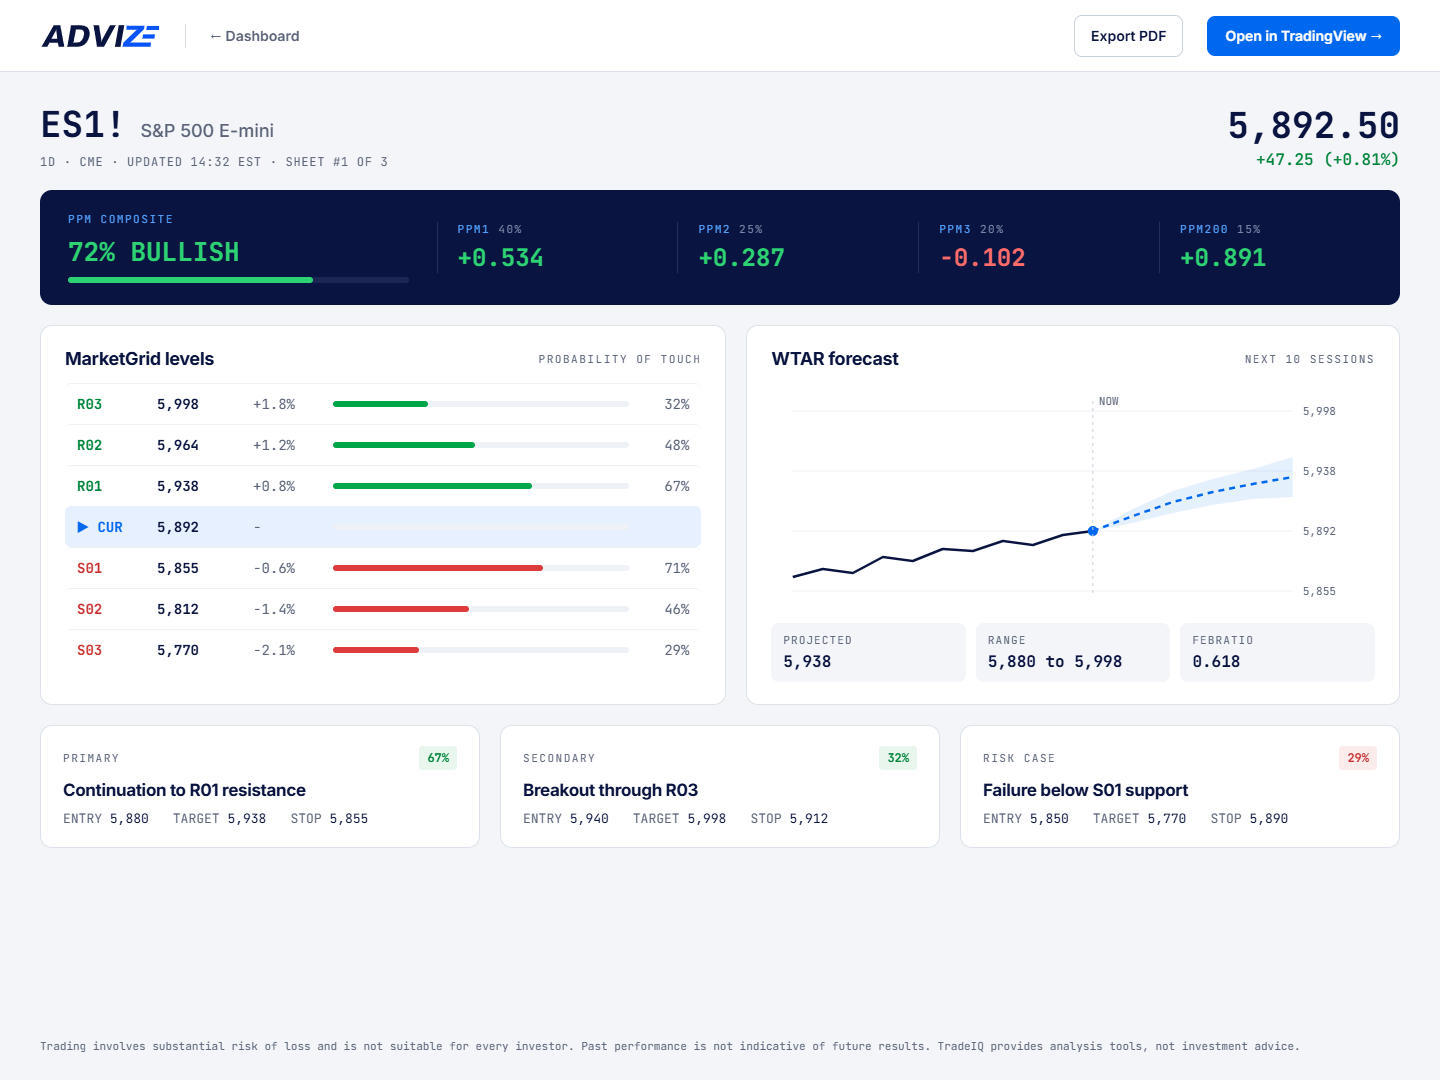
Protecting institutional capital goes well beyond gut-feel decision-making — it demands mathematically validated risk frameworks engineered for the realities of live markets. The PRISM risk dashboard from Advize.io meets that standard by uniting proprietary momentum scoring with automated pattern recognition mapped across probability grids. Drawdown boundaries, volatility forecasting, and continuous stress evaluation are woven directly into the analytical workflow. The outcome is a disciplined, reproducible system that measures and quantifies exposure well before it escalates into meaningful loss. Advize.io traces its quantitative foundations to proprietary trading desks rooted in the Chicago Board of Trade dating back to 1979, and today the platform serves more than 3,000 registered investment advisors whose decisions influence upward of $275 billion in institutional assets worldwide. Rather than relying on discretionary chart reading, the platform's empirically tested probability models bring a rules-based discipline to every analytical output. Active institutional traders and registered investment advisors turn to Advize because its methodology is rigorous, structured, and grounded in over four decades of continuous quantitative refinement. Every signal, scoring output, and forward projection reflects that depth of research.
Quantitative Risk Analytics Built for Institutional Portfolios

Inside the PRISM Risk Dashboard from Advize.io

Powerful features designed for modern teams
Portfolio Drawdown Architecture and Volatility Forecasting
Portfolio Drawdown Architecture and Volatility Forecasting

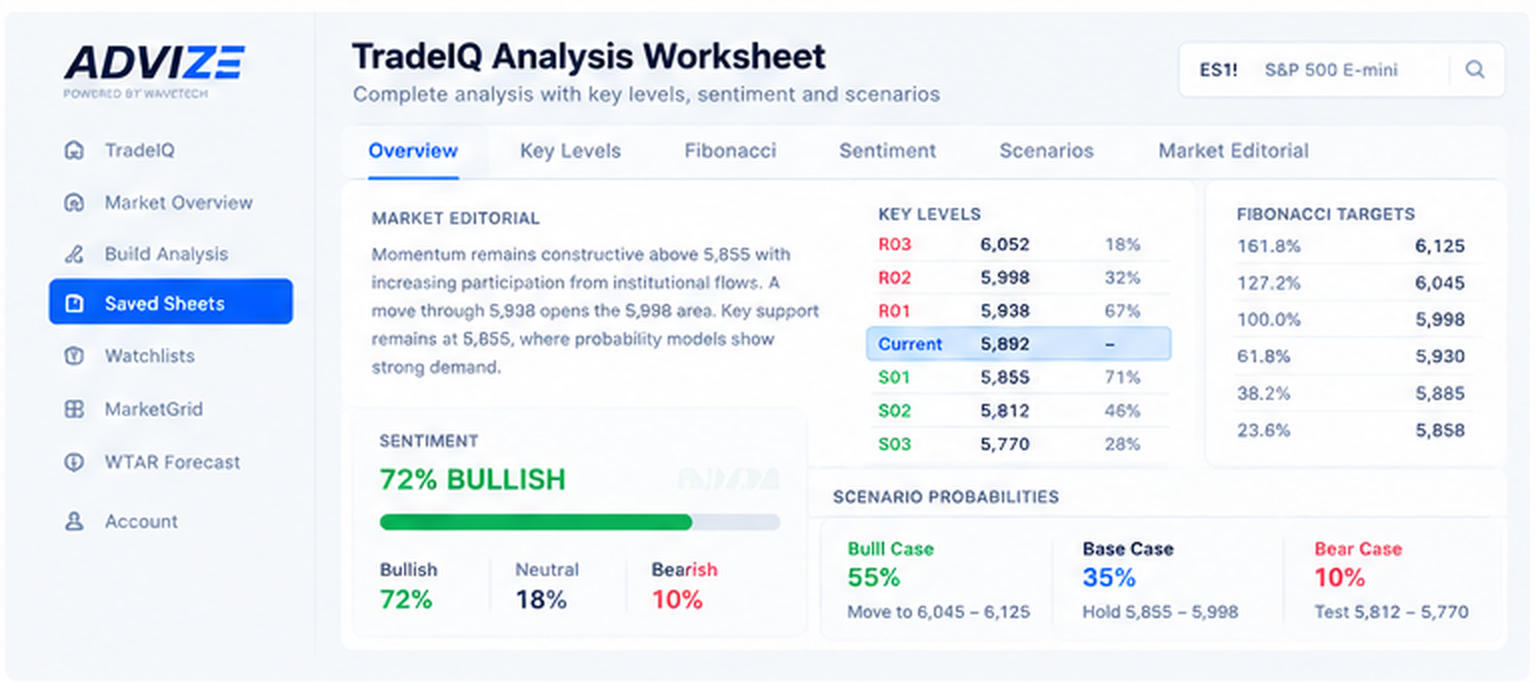
Unchecked drawdowns stand among the most destructive forces facing institutional portfolio management, capable of wiping out years of compounded returns across a matter of weeks. Within Advize.io, the PRISM system applies proprietary momentum scoring to continuously assess exposure thresholds across multiple asset classes simultaneously. Crucially, PRISM's volatility modeling operates in an anticipatory mode rather than a reactive one — it cross-references historical variance patterns with live probability grids to identify elevated risk conditions before they fully develop. Portfolio managers receive clearly defined, quantified drawdown limits rather than vague or subjective risk estimates. This empowers capital allocation decisions to be anchored to measurable confidence intervals instead of interpretive judgment. For registered investment advisors overseeing diversified books of business, these structured controls represent the difference between disciplined risk governance and unmanaged exposure accumulation. Explore the professional PRISM risk dashboard in Dewey to understand how drawdown architecture functions across actively managed portfolios.
Continuous Stress Scenario Testing and Probability Grid Analysis
Continuous Stress Scenario Testing and Probability Grid Analysis

Effective stress testing in institutional quantitative finance must capture market conditions as they unfold in real time, not as they were summarized in a prior-quarter report. PRISM conducts ongoing stress scenario evaluations, running capital exposure models against adverse market simulations drawn from decades of empirical price behavior data. Probability grid mapping then overlays outcome distributions across multiple forward time horizons, equipping portfolio managers with a prospective risk topology rather than a retrospective compliance audit. Every stress scenario is calibrated using Fibonacci-derived price targets combined with multi-period momentum sequencing, ensuring that stress outputs correspond to structurally significant price levels in the market. visit myportfolioadvisor.io gives institutional users direct access to these capabilities, enabling advisors to test portfolio resilience against scenarios spanning moderate volatility spikes through full liquidity stress events. The platform's mechanical methodology guarantees that all stress test results are reproducible, fully auditable, and entirely free from interpretive bias.
Capital Preservation Scoring and Rules-Based Institutional Positioning

Capital Preservation Scoring and Rules-Based Institutional Positioning

Capital preservation is not something that happens by default — it is an actively pursued objective that requires precise, continuously refreshed metrics to sustain. Advize.io's PRISM module generates capital preservation scoring through a structured, rules-based analytical framework that evaluates momentum signals, volume confirmation, and trend bias in parallel. Institutional traders and registered investment advisors on the platform receive quantified positioning insights derived from the same foundational quantitative models originally developed on the Chicago Board of Trade trading floor in 1979. These preservation metrics are fully integrated with the Advize Portfolio Manager's multi-period forecasting engine, producing a unified view of risk-adjusted positioning across the complete portfolio lifecycle. Unlike discretionary approaches that leave room for emotional interference, PRISM's mechanically driven scoring system keeps capital allocation decisions grounded in data. Four decades of continuous refinement across proprietary trading environments have shaped a framework that institutional capital managers can depend on under demanding live market conditions.

Frequently Asked Questions

PRISM is a proprietary risk management module within Advize.io built specifically for institutional traders and registered investment advisors. It automates pattern recognition, applies momentum scoring, and overlays outcomes across probability grids to deliver a structured, repeatable approach to portfolio risk management.

PRISM continuously monitors exposure thresholds using proprietary momentum scoring models, defining clear and quantified drawdown boundaries across asset classes. This allows portfolio managers to establish and maintain structured risk limits rather than depending on subjective or discretionary assessments during periods of elevated market volatility.

PRISM employs anticipatory volatility modeling that maps historical variance patterns against current probability grids. Instead of reacting to volatility after it materializes, the system flags elevated risk states in advance, providing institutional managers with an early-warning framework built on more than four decades of quantitative research.

PRISM runs continuous stress scenario simulations calibrated with Fibonacci-derived price targets and multi-period momentum sequencing. Each scenario models capital exposure against adverse market conditions sourced from empirical price behavior, generating reproducible and auditable stress outputs that remain free from interpretive or discretionary bias.

PRISM generates capital preservation scoring by simultaneously evaluating momentum signals, volume confirmation, and trend bias. These metrics are integrated with multi-period portfolio forecasts, giving advisors a rules-based, quantified perspective on risk-adjusted positioning across the full portfolio lifecycle without requiring subjective judgment.

Ready to Transform Your Business?

Join thousands of companies already using our platform