Financing Ohio Rental Properties With DSCR Loans

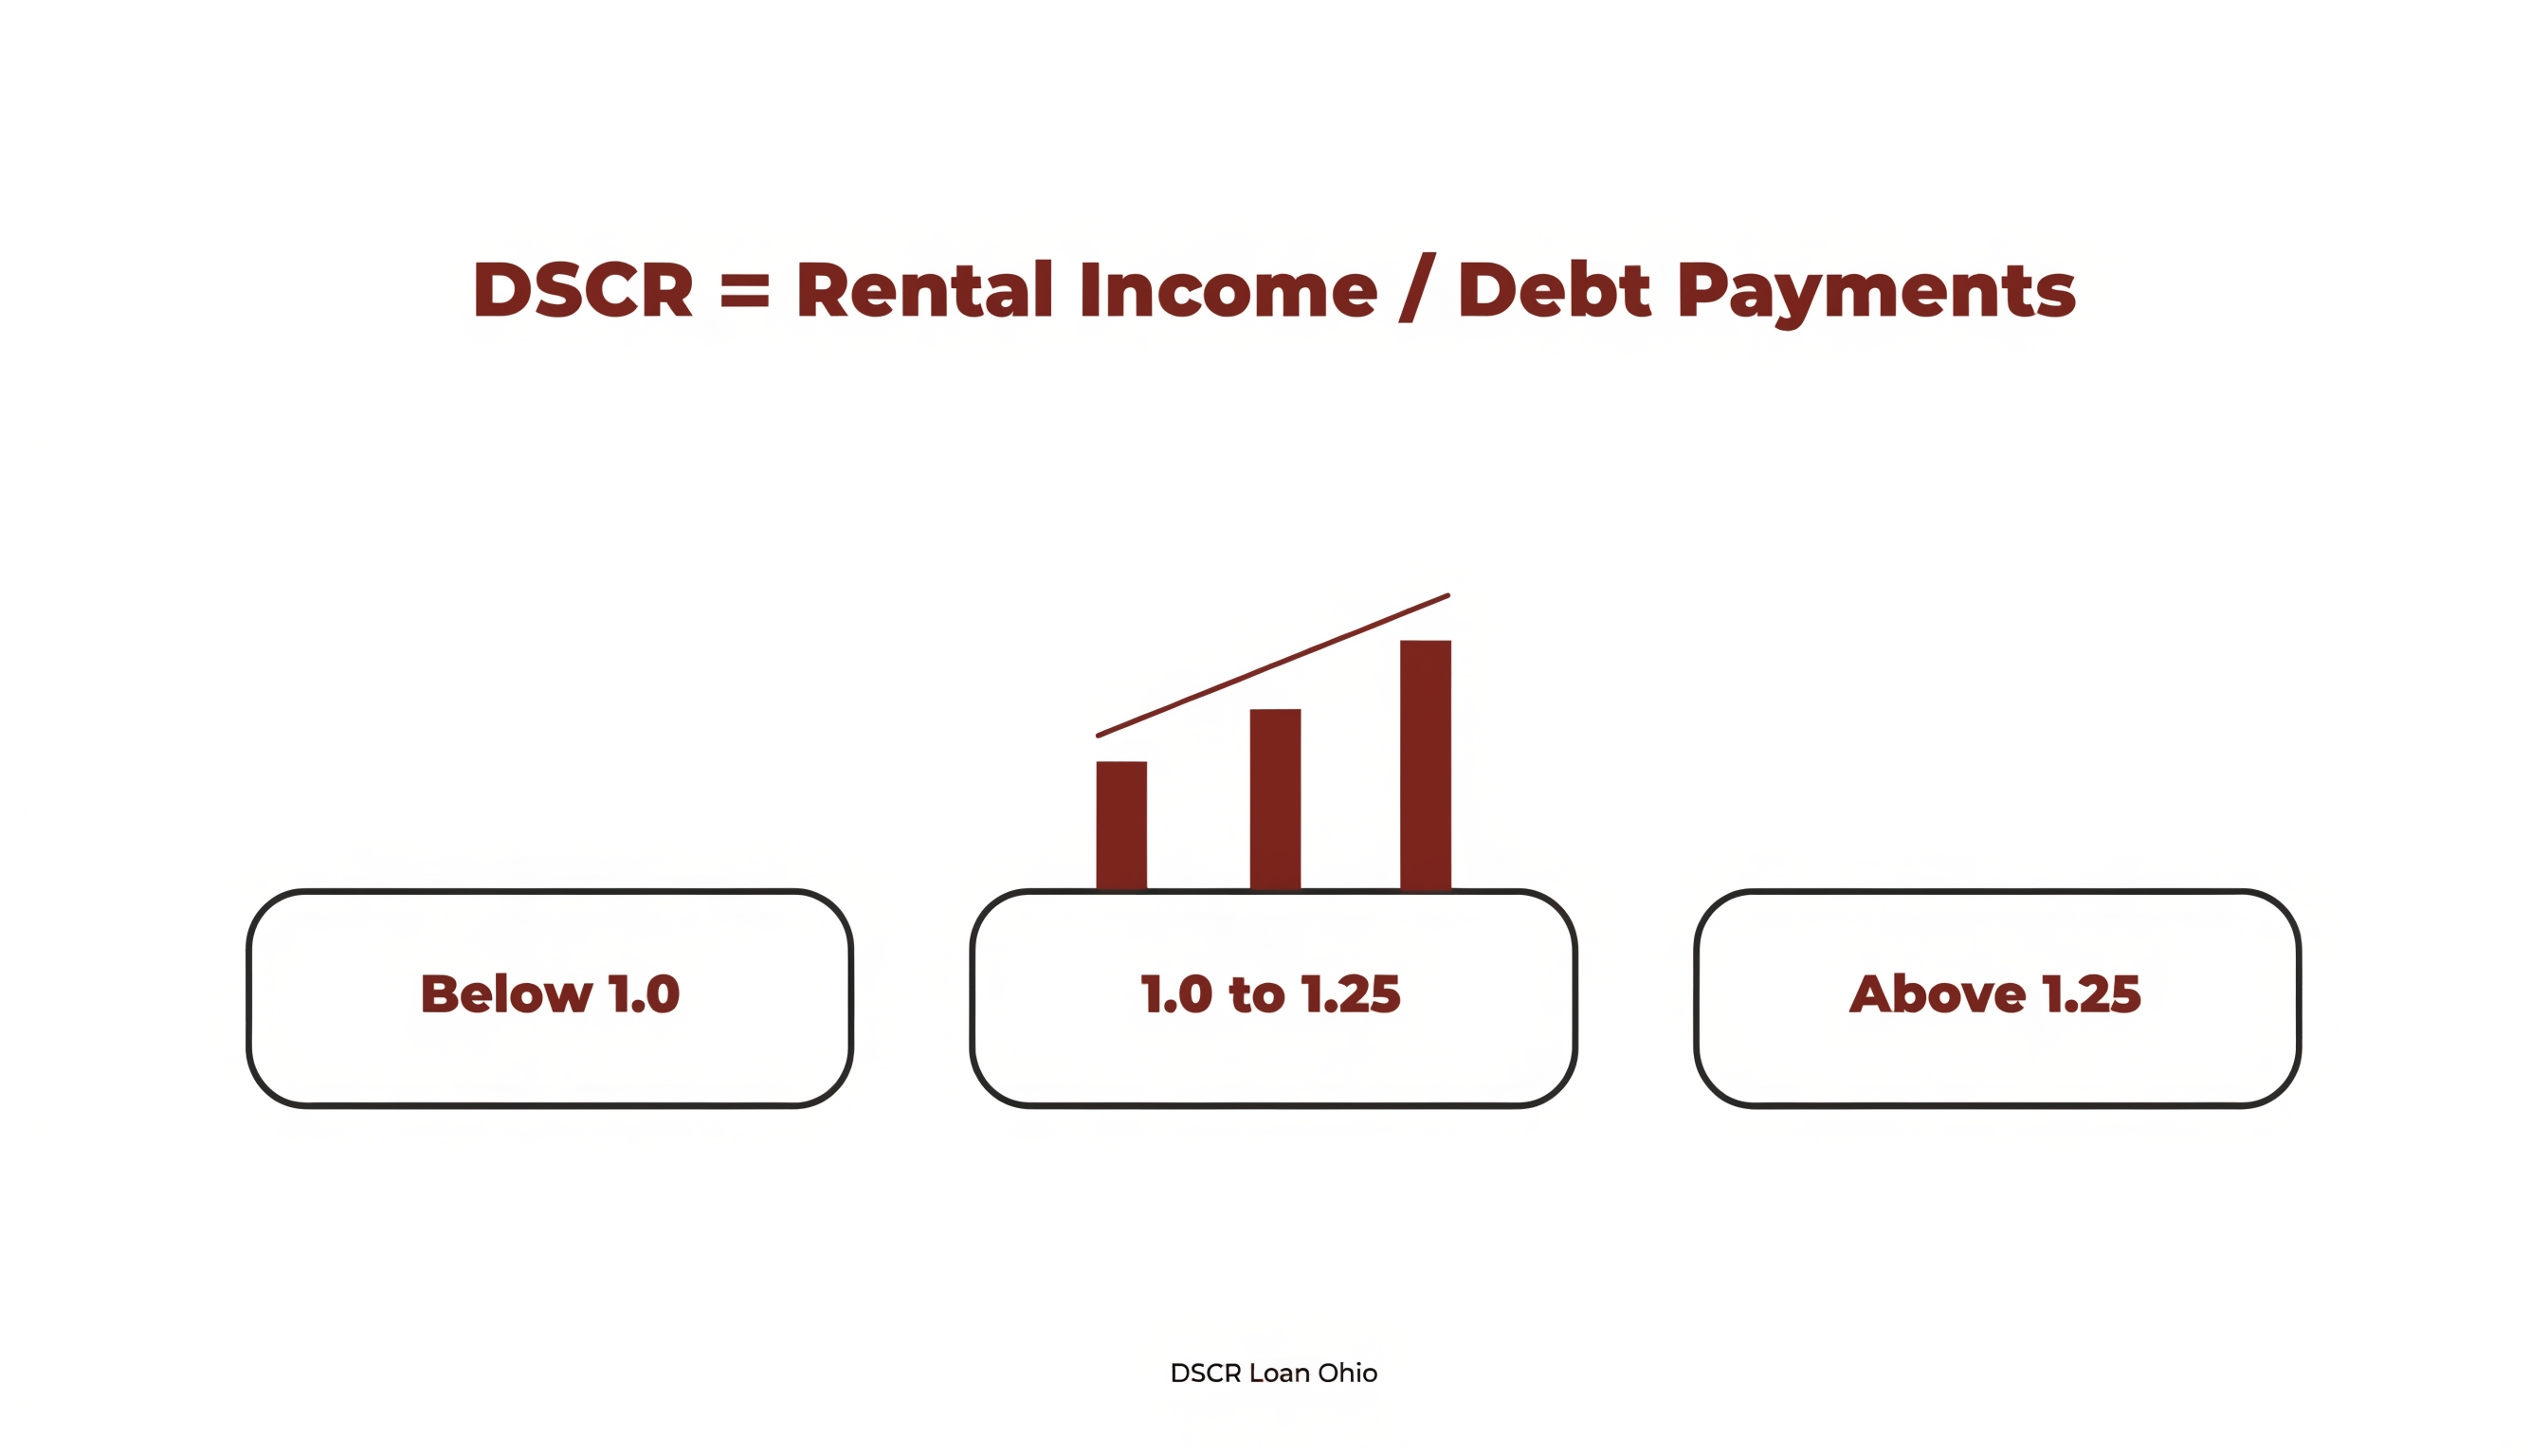
Savvy real estate investors are increasingly turning to Ohio as a prime destination for debt service coverage ratio financing, and it's easy to see why. Affordable acquisition costs, favorable rent-to-price ratios, and landlord-friendly legislation position Ohio among the most rewarding states for building a rental portfolio. DSCR Loan Ohio simplifies the lending process by matching investors with lender quotes evaluated on property cash flow rather than personal tax returns, making qualification more straightforward than traditional mortgage routes. Whether you're investing in Columbus, Cleveland, Cincinnati, or Akron, Ohio rental markets regularly produce gross yields that comfortably meet lender benchmarks. The core qualification principle is simple: monthly rental income must cover the mortgage payment, usually at a coverage ratio of 1.0 or above. Head to visit dscrloanohio.com to review live rate quotes and explore lending terms specific to Ohio investment properties. Knowing how debt service coverage ratio financing operates gives investors a decisive advantage in today's fast-moving market.
Financing Ohio Rental Properties With DSCR Loans
Financing Ohio Rental Properties With DSCR Loans

Understanding DSCR Calculations and Ohio Lender Thresholds
Understanding DSCR Calculations and Ohio Lender Thresholds

The debt service coverage ratio is determined by dividing a rental property's gross monthly income by its total monthly debt obligation, which encompasses principal, interest, property taxes, insurance, and any applicable HOA dues. A ratio of exactly 1.0 signals that rental revenue precisely meets the mortgage payment, though the majority of Ohio lenders prefer to see ratios between 1.10 and 1.25. Certain programs will approve ratios as low as 0.75 when the borrower presents strong credit and ample cash reserves. Income verification generally relies on either an executed lease agreement or a market rent opinion from a certified appraiser. Because Ohio properties are priced well below national averages, investors frequently exceed the 1.25 threshold without difficulty, particularly in growing markets like Dayton and Akron where rental rates have climbed more steeply than home prices over the past several years.
Key Ohio Markets and What Properties Qualify for This Financing
Key Ohio Markets and What Properties Qualify for This Financing

Each of Ohio's five primary metropolitan areas brings a unique set of strengths to rental property investment. Columbus stands out for its sustained population growth and consistently high tenant demand. Cleveland delivers some of the strongest gross rental yields found anywhere in the Midwest. Cincinnati offers stability rooted in a broadly diversified employment base, while Dayton and Akron attract investors with their exceptionally low acquisition costs and solid rent performance. Ohio-focused debt service coverage ratio lenders generally extend financing to single-family rentals, two-to-four-unit residential properties, and non-warrantable condominiums. Properties operating as short-term rentals may also be eligible when verified historical income data is available. Investors are strongly advised to confirm property eligibility directly with their lender prior to submitting an offer, as certain programs exclude properties in rural locations or low-density census tracts regardless of how favorable the coverage ratio may be.
Comparing Ohio Debt Service Coverage Ratio Loan Rates and Terms

Comparing Ohio Debt Service Coverage Ratio Loan Rates and Terms

Debt service coverage ratio financing in Ohio typically carries interest rates that run 0.5 to 1.5 percentage points higher than conventional investment property loans, a premium that reflects the absence of personal income verification. The rate a borrower receives depends on their loan-to-value ratio, credit profile, property type, and whether prepayment penalties are attached to the loan. Thirty-year fixed-rate mortgages are broadly available, and many lenders also offer five-year or seven-year adjustable-rate structures that start with lower initial rates. Interest-only periods are available through certain programs and can meaningfully improve cash flow in the early years of ownership. Rate structures vary considerably from one lender to another, so gathering multiple competing quotes is critical. Through DSCR Loan Ohio, investors can efficiently collect competing offers from several Ohio-focused lenders during a single session, allowing for a precise, apples-to-apples comparison based on the actual property rather than generic national benchmarks.

Frequently Asked Questions

The majority of Ohio lenders look for a minimum coverage ratio between 1.0 and 1.25, meaning rental income should at least fully cover the monthly mortgage payment. Certain programs will permit ratios as low as 0.75 when a borrower can demonstrate strong creditworthiness and adequate cash reserves.

Absolutely. Because these loans are evaluated on property income rather than the borrower's personal earnings, out-of-state investors are well-positioned to qualify. Lenders assess the rental potential of the Ohio property itself, not where the borrower resides or is employed.

Lenders most commonly accept a fully executed lease agreement or an appraiser-prepared market rent analysis. For properties that are currently unoccupied, a licensed appraiser's rent estimate is typically sufficient to satisfy the income documentation requirement.

Some lenders will finance short-term rental properties provided the borrower can supply documented historical income, typically sourced from platforms like Airbnb. Approval is contingent on consistent occupancy records and compliance with the lender's specific program criteria for that property category.

DSCR Loan Ohio Charleston connects investors with multiple Ohio-focused lenders so they can compare competing rate quotes in one place, using actual property data rather than generic national averages.

Ready to Get Started?

We'd love to hear from you