Florida Hurricane Damage Claims and Your Public Adjuster

When Hurricane Isaias swept through Florida, it left behind widespread roof destruction, flood intrusion, and severe structural harm that pushed thousands of property owners into the insurance claims process. Going it alone against an insurance company can be an uphill battle, particularly when carriers underestimate the full scope of repairs needed. Rockwall National Public Adjusters in Midlothian represents only policyholders — never insurers — making sure every covered loss is thoroughly documented and vigorously pursued. Their licensed professionals bring over two decades of hands-on experience, guiding clients through each phase from initial inspection to final settlement. Whether your property endured wind destruction, moisture infiltration, or a complete loss, a knowledgeable advocate significantly improves your financial recovery. Acting without delay is essential because Florida insurance policies impose tight deadlines that can limit your ability to collect what you are owed.
Florida Hurricane Damage Claims and Your Public Adjuster

Expert Public Adjuster Support for Florida Hurricane Isaias Property Claims
Comprehensive Damage Inspection Following Hurricane Isaias
Comprehensive Damage Inspection Following Hurricane Isaias

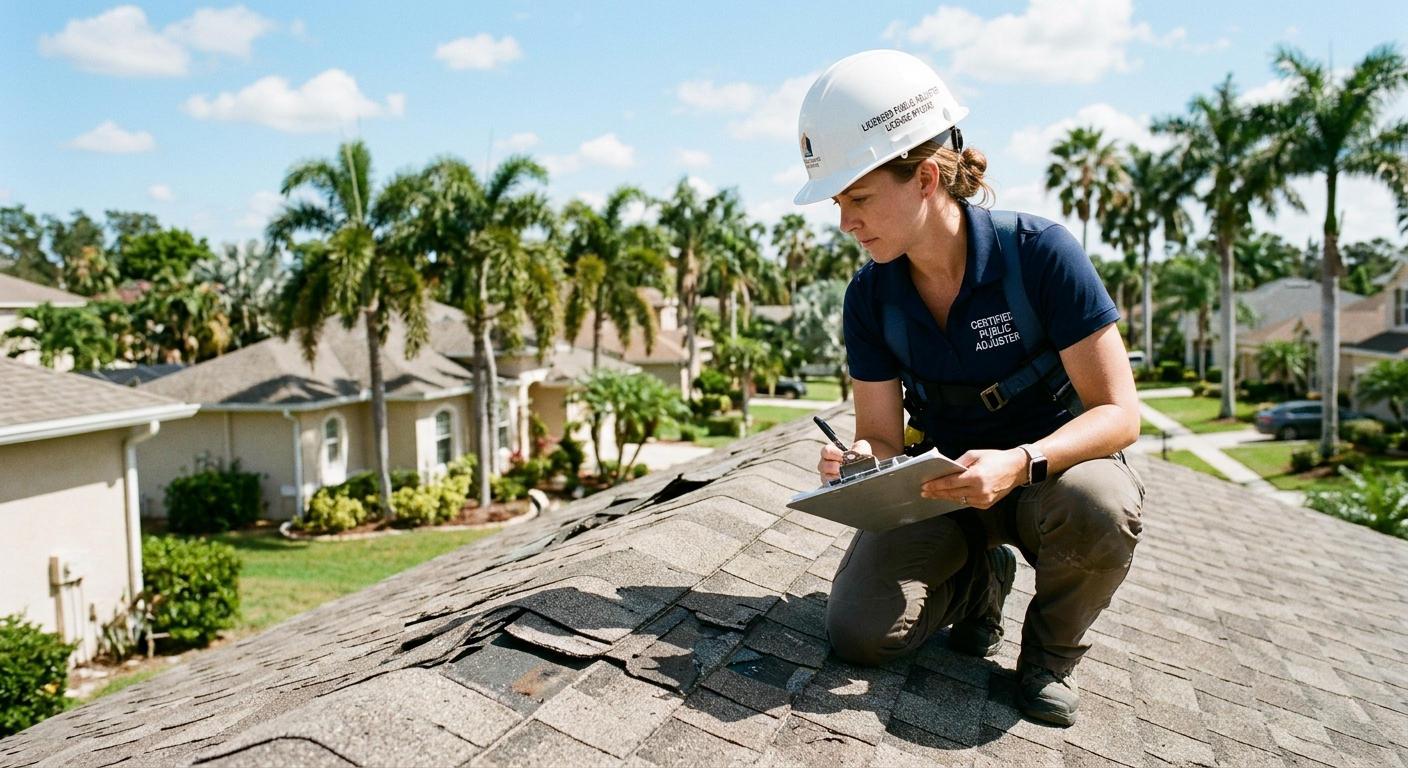
A properly documented Florida property damage insurance claim begins with a detailed, professional inspection that leaves nothing to chance. In the aftermath of Hurricane Isaias, countless properties across the state suffered concealed damage to roofing structures, interior framing, and electrical systems that a cursory insurance company inspection would likely undervalue or overlook altogether. Rockwall National Public Adjusters performs a systematic, space-by-space evaluation using industry-recognized estimating platforms and seasoned inspectors who understand precisely which items carrier-employed adjusters tend to miss. Every compromised component is photographed, measured, and priced at current market replacement values, assembling a claim package that stands up to insurer scrutiny. This rigorous methodology protects policyholders from unknowingly accepting inadequate settlements that fail to cover the true cost of restoring their property.
Understanding Policy Deadlines and Coverage Terms in Florida
Understanding Policy Deadlines and Coverage Terms in Florida

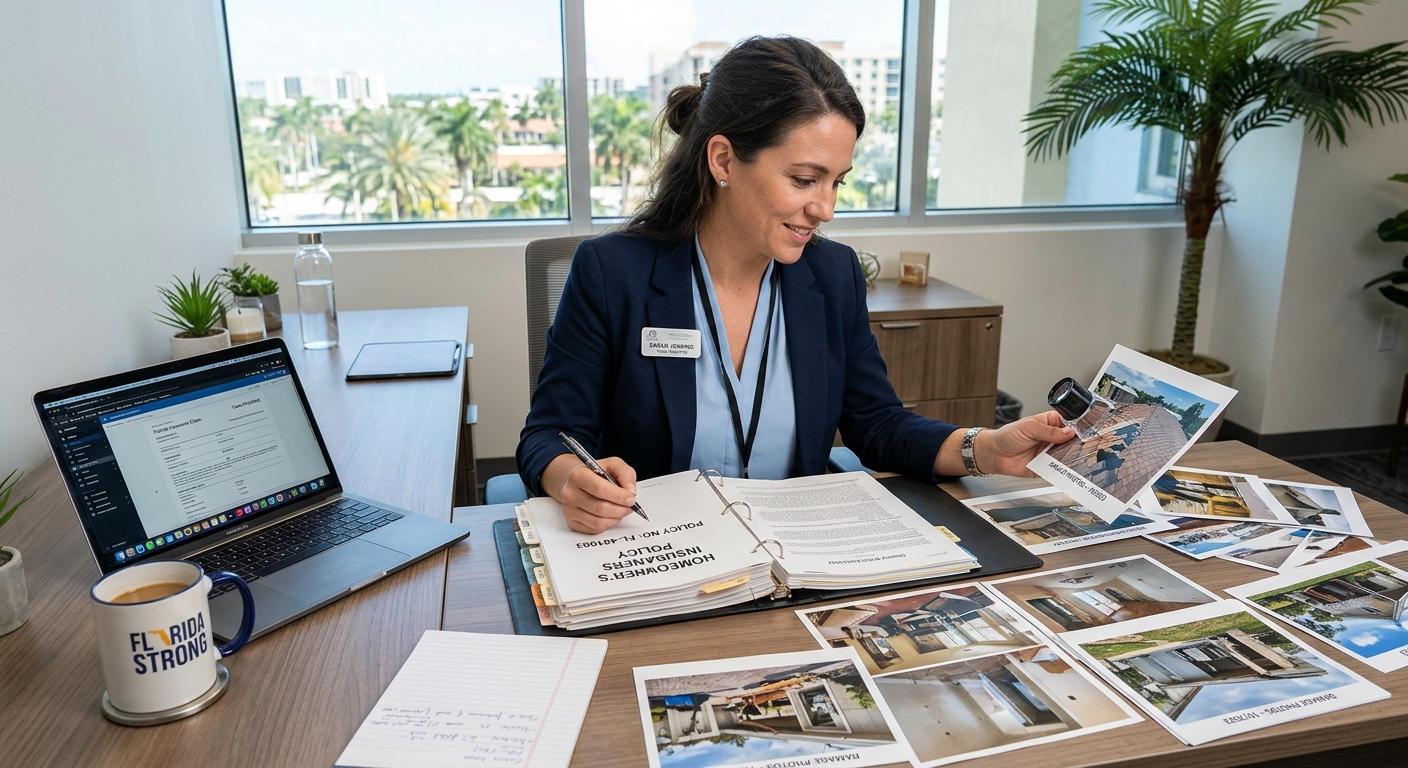
Florida homeowner and commercial property insurance policies include precise notice obligations, proof-of-loss submission windows, and coverage stipulations that policyholders must fulfill to prevent their claim from being denied or diminished. If your property sustained hurricane damage during storm season and you have not yet initiated a claim, the clock is already working against you. The professionals at rockwallnpa.com examine every line of your policy, pinpointing all relevant coverages, endorsements, and exclusions before any documentation reaches your insurer. Distinguishing between actual cash value and replacement cost provisions, understanding your deductible structure, and recognizing flood-related exclusions can translate into tens of thousands of additional dollars recovered. For those still managing hurricane-related property damage claims in Florida, requesting a policy review right away is among the most valuable actions available.
Strategic Insurer Negotiations to Maximize Your Claim Settlement

Strategic Insurer Negotiations to Maximize Your Claim Settlement

Carriers deploy experienced adjusters, in-house legal counsel, and proprietary valuation software specifically engineered to reduce claim payouts — property owners seeking fair compensation deserve equally skilled representation in their corner. Rockwall National Public Adjusters manages all insurer correspondence and settlement negotiations directly, presenting a thoroughly substantiated, professionally constructed claim designed to achieve the highest defensible payout. When a carrier undervalues or stalls on Hurricane Isaias claims Florida policyholders are entitled to pursue, Rockwall is prepared to escalate through alternative dispute resolution channels including appraisal, arbitration, and mediation. The firm further provides litigation support by drafting expert reports and appearing as witnesses when matters proceed to court. Time and again, clients attain considerably greater recoveries than they could achieve through independent negotiation.

Frequently Asked Questions

A public adjuster catalogs all property damage in detail, interprets the language of your insurance policy, and negotiates directly with your insurer on your behalf. The objective is to secure a complete and accurate claim payout rather than a lowball settlement that benefits the insurance company.

Florida law imposes firm deadlines for reporting hurricane damage and submitting proof-of-loss documentation. If you think your window may have closed, reach out to a licensed public adjuster right away to have your policy reviewed and find out whether a late-notice submission or reopened claim remains a viable option.

Most Florida public adjusters operate on a contingency basis, collecting a percentage of the settlement amount they recover for you. There are no out-of-pocket costs upfront, and the fee is only due once funds have been successfully recovered from your insurance company on your behalf.

Absolutely. When an insurer has denied or short-paid a claim, a public adjuster can reopen the file, introduce additional supporting documentation, and pursue appraisal or mediation. Numerous policyholders have obtained substantially greater settlements even after an initial denial or inadequate offer.

Public adjusters manage claims involving roof damage, wind-driven rain infiltration, structural deterioration, water intrusion, storm-related mold, and complete property losses. They also document harm to personal belongings, detached structures, and business inventory under applicable homeowner or commercial policies.

Ready to Get Started?

We'd love to hear from you