Why Advisors Trust the Advize Portfolio Manager
The Advize portfolio manager is a precision-engineered quantitative platform designed for registered investment advisors and active traders who require empirical rigor rather than subjective interpretation. Built by NEXT GEN Global Partners, LLC and drawing on methodologies forged on the Chicago Board of Trade trading floor, it substitutes mathematically validated probability models for discretionary chart reading. The platform currently supports more than 3,000 registered investment advisors and has shaped positioning decisions across more than $275 billion in institutional assets globally. Its institutional-grade architecture produces multi-period forecasts alongside Fibonacci-calibrated price targets, offering a structured and repeatable analytical foundation. Advize unifies three purpose-built tools — TradeIQ, PRISM, and the portfolio manager — into one seamless quantitative workflow. Advisors and traders throughout Arizona and across the country rely on Advize.io in Dewey to shift from reactive, sentiment-driven decisions toward a disciplined mechanical methodology. Continuous real-time analytics and mathematically grounded asset allocation modeling ensure every position is measured against probability grids rather than market narratives. From concentrated equity books to diversified multi-asset strategies, Advize equips modern advisors with the quantified positioning clarity their clients expect.
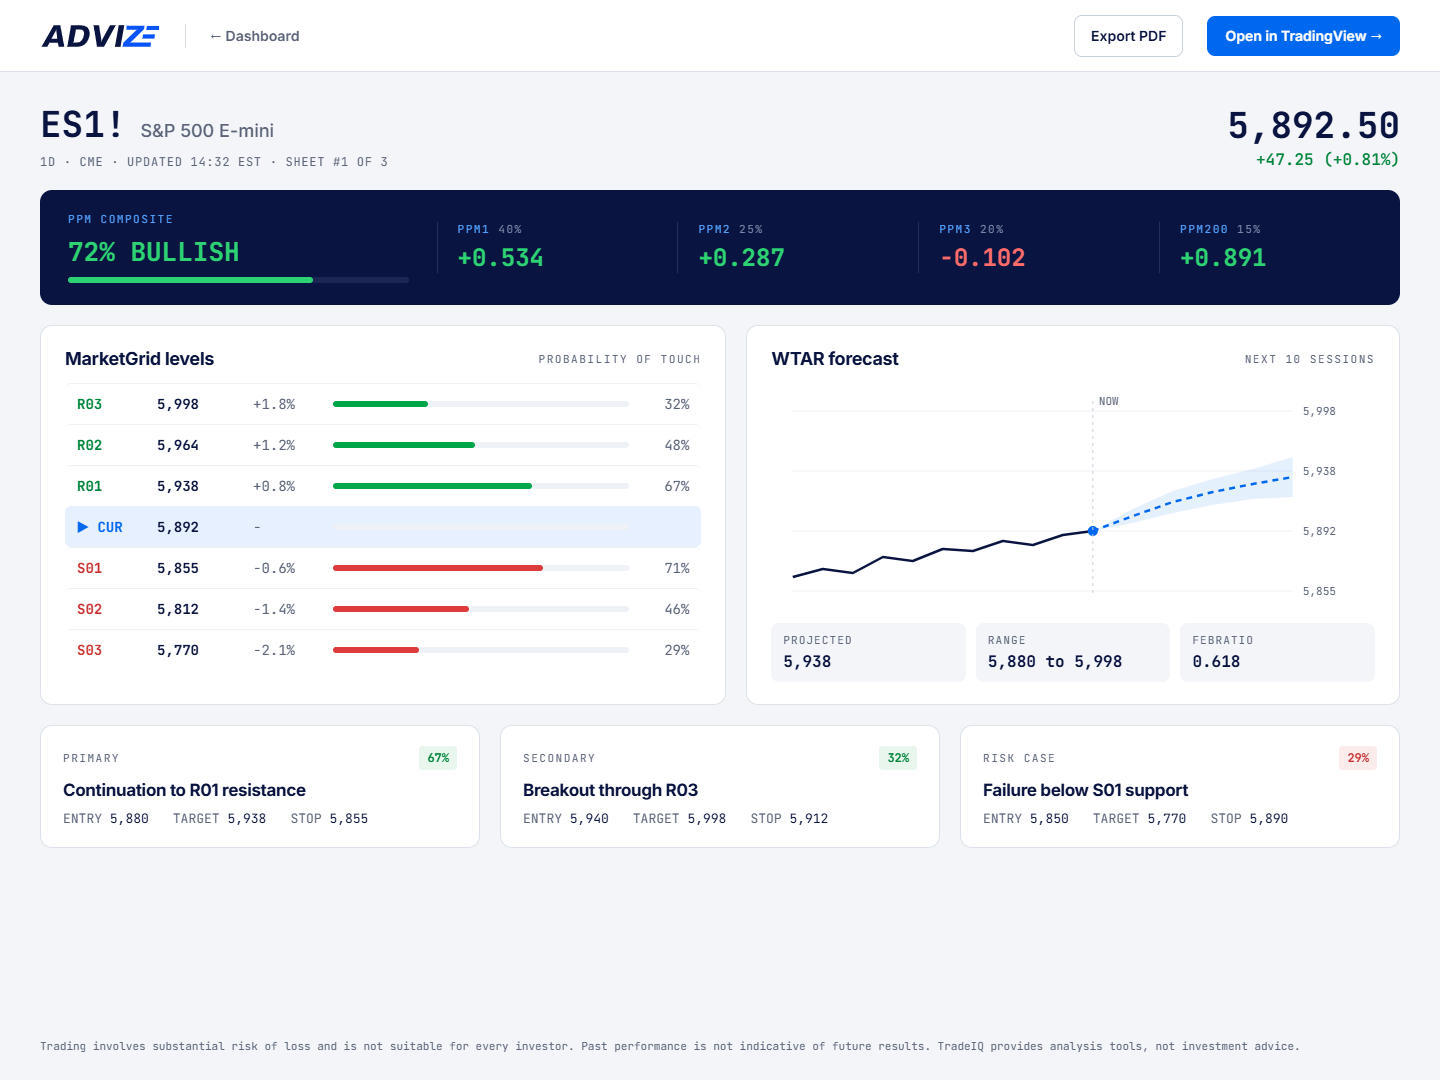
An In-Depth Look at the Advize Portfolio Manager
Powerful features designed for modern teams
Continuous Quantitative Tracking Across Multiple Time Horizons
Probability-Driven Allocation Weightings and Systematic Rebalancing
Live Performance Analytics Built for Institutional and Advisor Standards
Frequently Asked Questions
The Advize portfolio manager is a quantitative positioning tool engineered for registered investment advisors and active traders. It generates multi-period forecasts and Fibonacci-calibrated price targets, replacing subjective chart analysis with a structured, mathematically validated methodology suited to institutional and professional-grade use.
Advize pulls live data from TradingView feeds and applies its nine-part TradeIQ analysis to each holding on a continuous basis. This simultaneous tracking of trend bias, volume confirmation, and momentum sequencing gives advisors a real-time, multi-asset view grounded entirely in quantitative probability models rather than manual interpretation.
Advize evaluates allocation weightings through PRISM's probability grids and momentum scoring, applying a mathematical rather than a subjective lens. Each optimization signal emerges from pattern recognition algorithms instead of analyst opinion, ensuring every allocation decision is documented, reproducible, and backed by empirical quantitative evidence.
When a position moves outside its quantitatively defined optimal band, Advize produces structured rebalancing signals derived from PRISM's probability output. This process eliminates emotional judgment from rebalancing decisions, lowers unnecessary transaction costs, and keeps the portfolio aligned with its strategic goals across shifting market conditions.
Yes. Advize structures its performance analytics to align with the documentation standards that registered investment advisors must meet. Every metric traces back to a defined quantitative model, providing the transparent and auditable reporting trail required by both internal compliance processes and client-facing communication.
Ready to Transform Your Business?
Join thousands of companies already using our platform